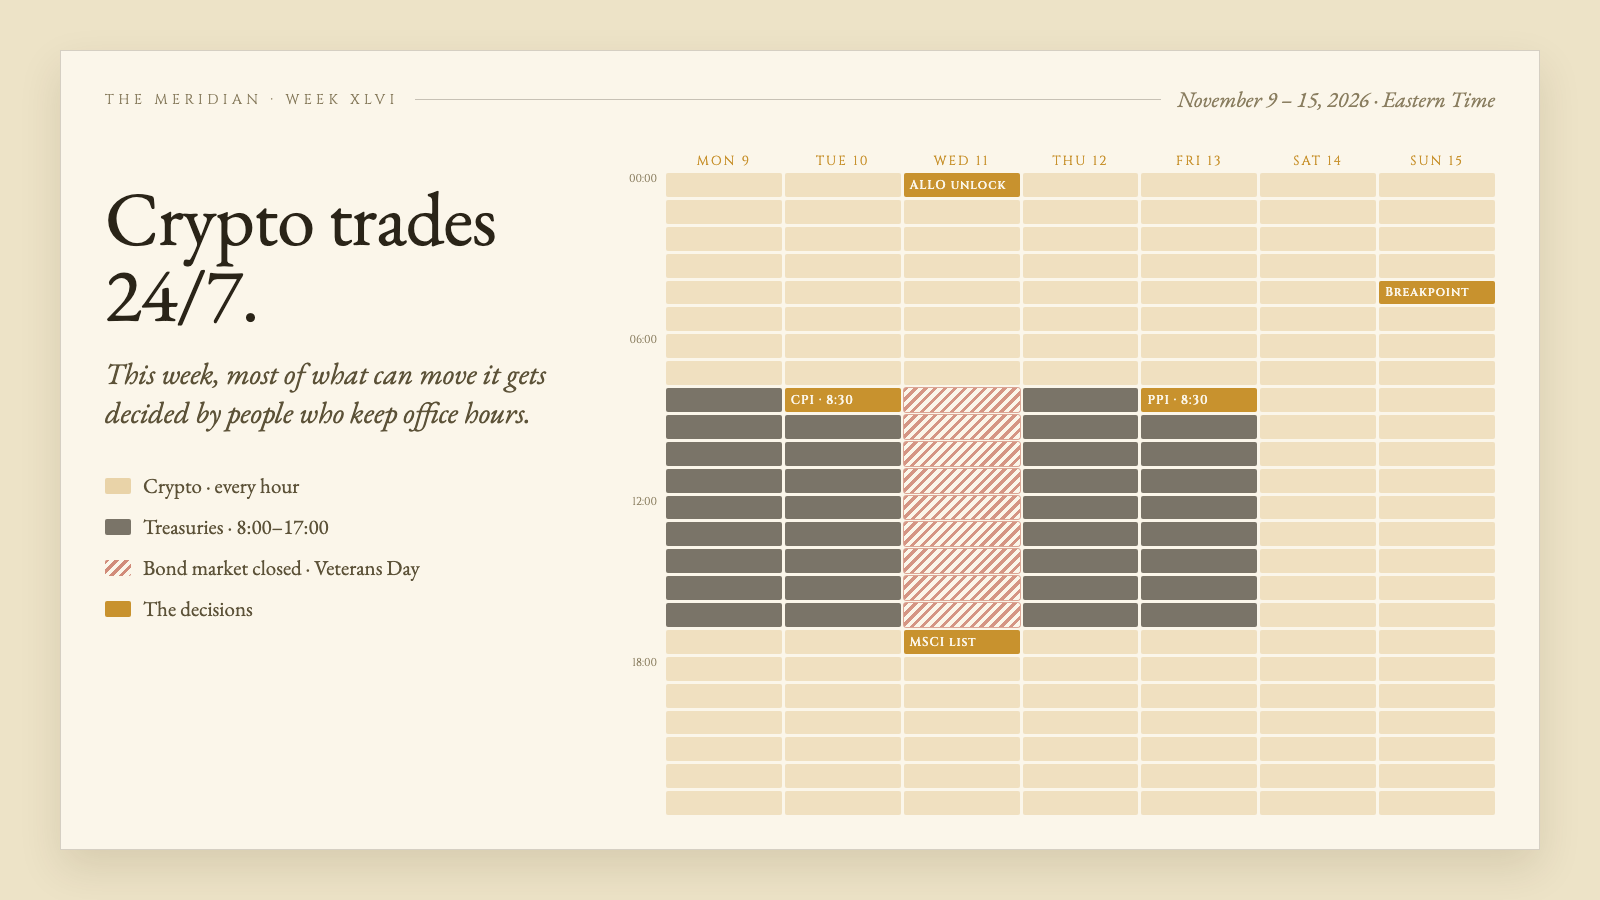
Crypto trades 24/7. This week, most of what can move it gets decided by people who keep office hours.
One market never closes. The other one keeps office hours.
The last inflation print before the Fed's December 8–9 meeting.
The backdrop
Fear & Greed is sitting in the high 20s, spot Bitcoin ETFs lost about $1.28B last week, and Binance is still reopening withdrawals network by network after the $6.3B hack.
Tuesday: a CPI with a hole in it
Tuesday is October CPI, the last inflation print before the Fed meets on December 8–9. After payrolls came in at 165K against roughly 60K expected, futures price about 75–80% odds of a hike.
One detail most people will miss: the 2025 shutdown erased last October's data, so there is no official annual CPI rate this time. Only monthly changes. If you see a year-over-year number, someone modeled it.
No official answer. October 2025 prices were never collected, so October 2026 has nothing to compare to. Watch the monthly change instead.
Wednesday: the bond market steps away
Wednesday, the US bond market closes for Veterans Day. Treasuries get one session to react to CPI, then step away. Crypto keeps digesting it alone.
That evening, MSCI publishes its November index review, the first under its new rules for non-operating companies. Strategy and Metaplanet were both flagged in its earlier simulation. An older JPMorgan estimate put the outflows near $2.8B for MSTR alone if it is cut.
Passive funds follow index rules, not Bitcoin conviction.
The changes take effect around November 30, but markets rarely wait that long to price it. One caveat worth keeping: under the new framework, current members are removed only after failing the screen in two consecutive annual periods, so how fast this bites is still an open question until the list is out.
Same day: the ALLO cliff
Also on Wednesday, about 160M ALLO from Allora Network's first backer and core contributor cliff is scheduled to unlock. Depending on the tracker, that's 63–80% of circulating supply. That much float into weak demand is a real test.
Friday: a second read on October
Friday's PPI gives a second read on October, after a 1.3% month-over-month jump in September.
Sunday: Breakpoint
Sunday, Solana Breakpoint opens in London, with DTCC, Mastercard and Boris Johnson on the speaker list. I care less about the announcements and more about which products pull real users and liquidity after.
Not the headlines on stage, but the weeks after: new users, new liquidity, and whether either one stays.
So the question I keep asking this week: who is forced to act?
We don't need another narrative right now. We need buyers.
Sources
Where sources disagree, the range is shown. Times are US Eastern.
- CPI without a 12-month rate: Stock Titan, the November 10 CPI will have no yearly rate; Morningstar, October CPI forecasts.
- Payrolls and hike odds: Fox Business, 165,000 jobs; InvestmentNews, December hike odds; Morningstar, odds at 79%.
- ETF flows and sentiment: The Crypto Times, $1.28B weekly outflows; CoinGabbar, Fear & Greed at 28; Blockchain Reporter, Binance withdrawals reopen.
- Bond market holiday: SIFMA, Veterans Day close recommendation.
- MSCI: MSCI, November 2026 index review timing; The Block, the finalized rules; Decrypt, Strategy faces removal; Invezz, JPMorgan's $2.8B estimate.
- ALLO unlock: Tokenomist, Allora; CryptoTicker, 160M ALLO on November 11.
- PPI: BLS, September 2026 PPI and the October release date.
- Breakpoint: Solana, the London lineup.
 Post on X
 Telegram